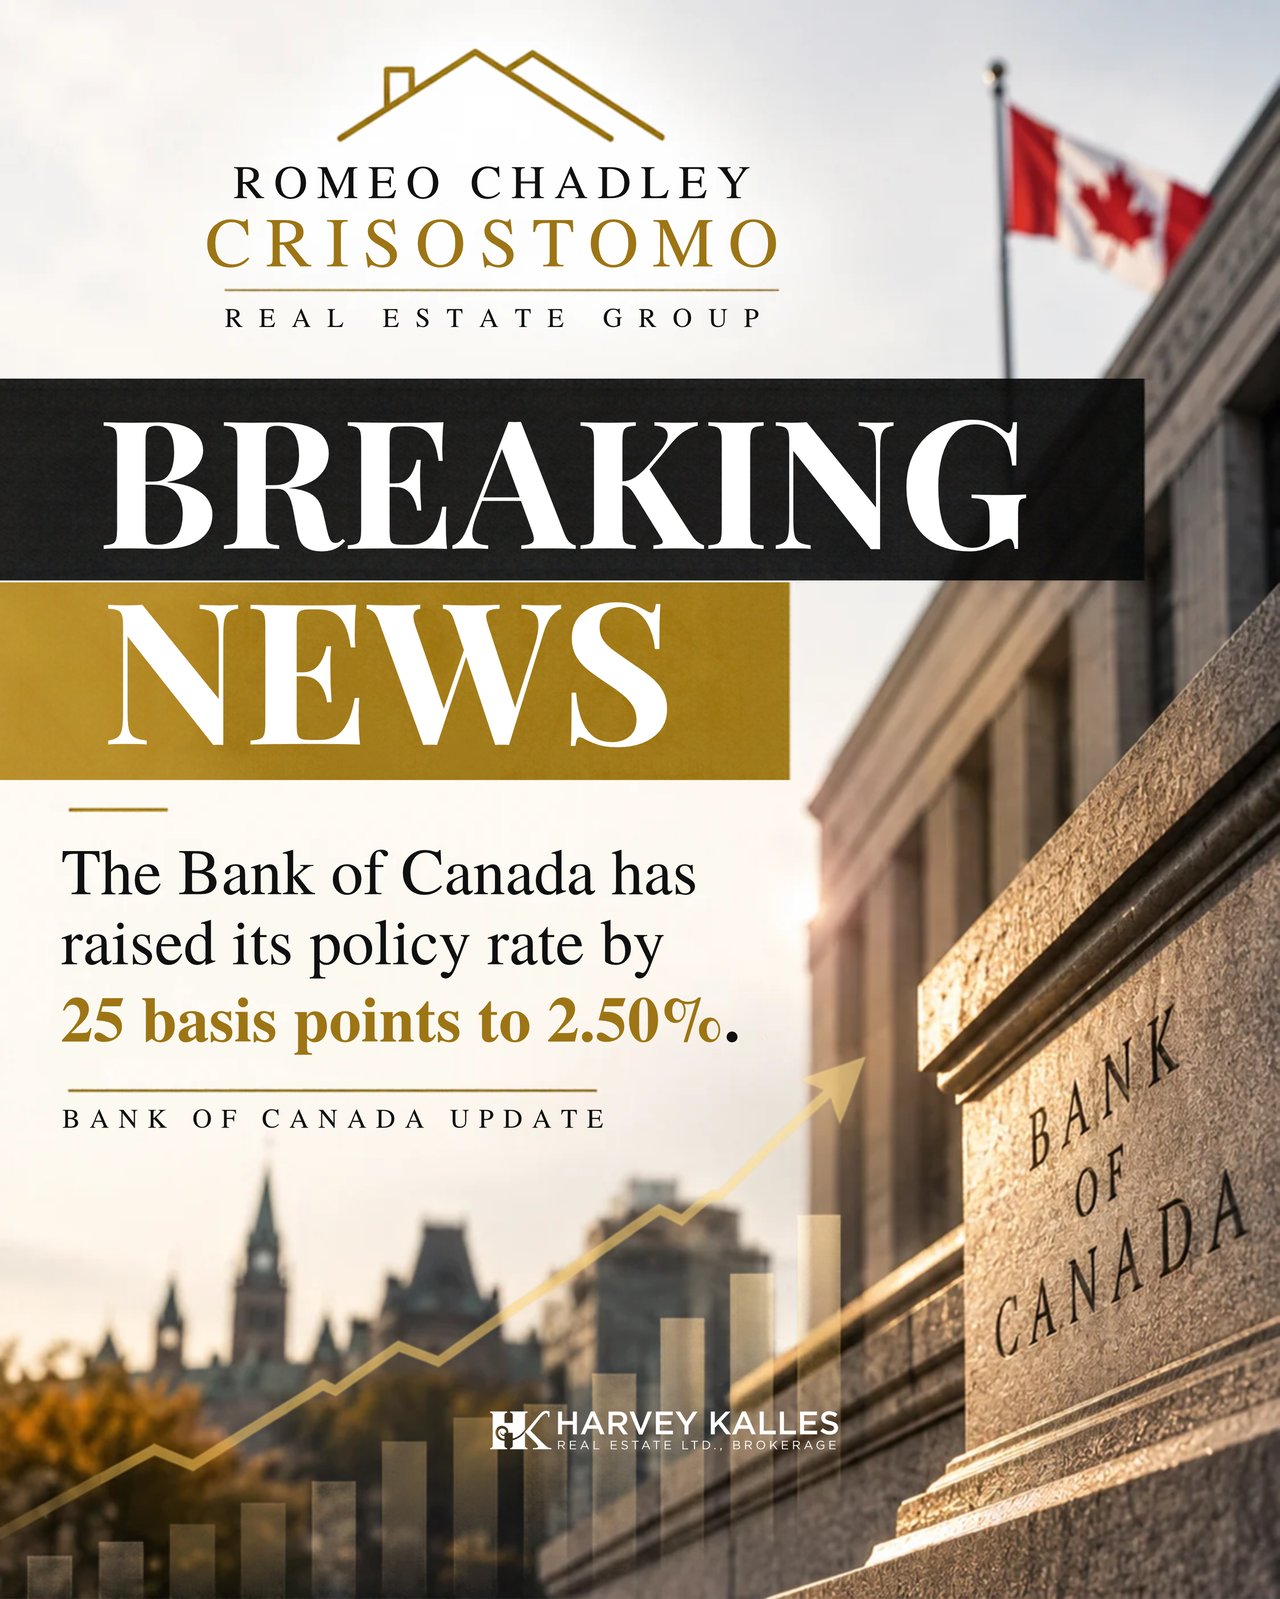
The Bank of Canada just raised its policy rate by 25 basis points to 2.50%. The first increase since July 2023.
So, does this mean you should put your real estate plans on hold?
Not necessarily. But it does mean we need to look at the numbers a little more carefully.
Let's put things into perspective.
According to TRREB, September 2026 saw GTA home sales decline by 9%, new listings fall by 14.4%, and the average selling price drop by 5.1% compared to September 2025.
That's a market where buyers are being more selective, sellers need to be realistic, and opportunities depend heavily on the property and location.
Here's what we're advising our clients.
🏡 BUYERS: Don't confuse a rate increase with a reason to stop looking.
Yes, borrowing costs matter. But so does the price you negotiate. With GTA average selling prices below last year's levels, some properties may offer opportunities that weren't available before.
Our advice? Get your financing reviewed, understand what you can comfortably afford, and let us examine comparable sales before making an offer. If the numbers don't work, we walk away. There will be other homes.
🏠 SELLERS: Today's buyers need a good reason to choose your property.
Fewer new listings don't automatically mean an easier sale, especially when sales activity has also slowed.
This is not the market for guessing your asking price. We look at recent sales, competing listings and what buyers are actually responding to. A well-prepared home with a realistic price can still attract serious interest.
📈 INVESTORS: A lower purchase price is only a good deal if the numbers work.
We look beyond the listing price. Mortgage payments, rental income, vacancy risk, condo fees, property taxes and maintenance all need to be accounted for.
And with the possibility of further rate increases, your investment should still make sense if borrowing costs rise again.
Here's something else worth remembering.
The Bank of Canada raised rates partly because inflation remains a concern, even as economic growth has been stronger than expected. The economy is showing some resilience, but the Bank still expects housing activity to remain relatively weak.
So we're not calling this a booming market, and we're certainly not telling everyone to rush out and buy.
After more than 20 years in real estate, we've learned that the best time to make a move is when the property, the price, the financing and your personal circumstances make sense together.
The rate may have changed. Your goals haven't. But perhaps your strategy should.
If you're buying, selling or considering an investment in the GTA, let's review your options based on actual market data, not speculation.