Filipinos are very good at working hard.
We work overtime. We save. We help family. We look for sales even when we can afford full price. And if something still works, why would we throw it away?
That mentality has helped generations of Filipino families build a life in Canada.
But when it comes to money, some of the advice we grew up hearing was designed mainly to protect what we have, not necessarily to grow it.
And before anyone sends this article to the family group chat with “Hoy, basahin mo ’to,” we are not saying Nanay and Tatay were wrong.
We are saying the world of real estate has changed, and some old assumptions deserve another look.
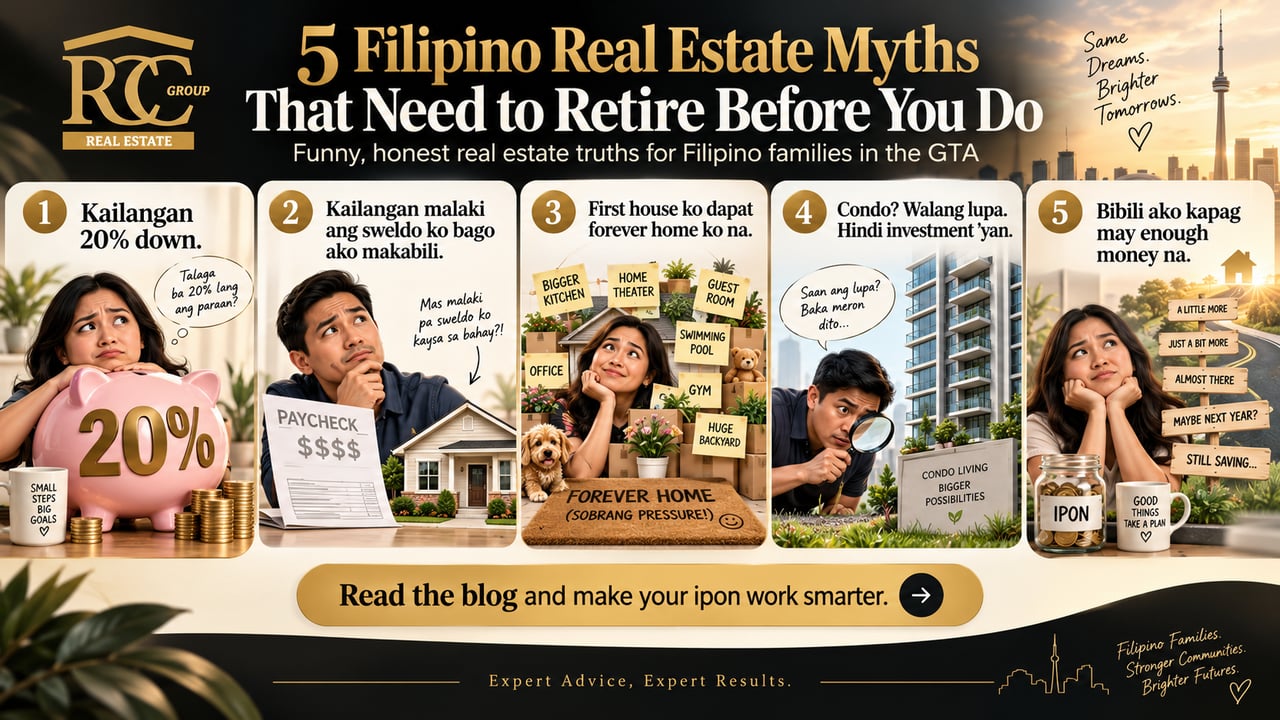
So here are five real estate myths we think are ready for retirement.
This number has somehow achieved legendary status.
You mention buying a home and somebody immediately asks:
“May 20% ka na?”
No?
Conversation over. Balik trabaho.
But 20% is not automatically required for every home purchase in Canada. For eligible owner-occupied properties, qualified buyers may be able to purchase with less than 20% down, although mortgage insurance and other rules can apply.
Now, does this mean everyone should put the smallest down payment possible?
Also no.
And if you are buying a property strictly as a rental investment, the financing rules can be different.
The point is simple: do not eliminate yourself from homeownership because somebody told you, “Twenty percent or nothing.”
Talk to a mortgage professional. Run the numbers.
You might discover that you are nowhere near ready.
Or you might discover:
“Ay... pwede pala.”
Both are better than guessing.
2. “Kailangan malaki ang sweldo ko bago ako makabili.”
Some people look at GTA real estate prices and immediately decide:
“Okay. Hindi para sa akin ’yan.”
No mortgage application.
No conversation with a lender.
No numbers.
Just immediate surrender.
Parang audition na hindi ka pumunta pero ikaw na rin ang nag-reject sa sarili mo.
Yes, income matters. Of course it does.
But your salary is only part of the picture. Lenders can also look at your debts, credit, down payment, monthly obligations and the property you want to buy.
You may not be able to afford the detached house with the double garage, giant backyard and kitchen worthy of a teleserye mansion.
But maybe that was never supposed to be your first move.
A condo, townhouse or smaller property may be the beginning.
You do not have to start rich to start building wealth.
You just have to know what you can realistically afford.
3. “First house ko dapat forever home ko na.”
This is where a simple first-home search can get completely out of control.
You start with:
“Something small is okay.”
Two weeks later:
Four bedrooms.
Finished basement.
Double garage.
Big backyard.
Excellent schools.
Near work.
Near parents.
Near the highway.
Preferably renovated.
And room for relatives visiting from Manila.
Starter home daw.
Starter mansion pala.
Your first property does not have to accommodate every possible version of your life until retirement.
Maybe your first home is a condo.
Later, you move to a townhouse.
Then perhaps a detached home.
Eventually, the children move out and you stand inside the giant house you spent twenty years trying to get and say:
“Ang laki naman nito. Sino maglilinis?”
And now we have come full circle.
Real estate can be a series of moves.
Your first home can help you build equity, learn how homeownership works and potentially put you in a stronger position for the next one.
It does not have to be your forever home.
It just has to be the right home for this chapter.
4. “Condo? Walang lupa. Hindi investment ’yan.”
Say the word condo around the wrong dinner table and prepare yourself.
“Pero wala kang lupa.”
Yes.
This is true.
You probably will not be planting an entire mango plantation outside Unit 1807.
But whether a property is a good investment cannot be decided by asking:
“May damo ba?”
Land can absolutely be valuable. But so can location, demand, affordability, rental potential and convenience.
A condo near transit, jobs, schools and amenities may make sense for one buyer.
A detached house with a yard may make more sense for another.
The property itself is only part of the equation.
The numbers matter.
The location matters.
The price you paid matters.
Your strategy matters.
Because buying a house simply because “at least may lupa” does not automatically make it a brilliant investment.
Grass is nice.
Grass is peaceful.
Grass also needs to be cut every Saturday.
5. “Bibili ako kapag may enough money na.”
This sounds like the most responsible plan in the world.
“Mag-iipon muna ako.”
Excellent.
One year later:
“Konti pa.”
Two years later:
“Next year siguro.”
Then the car needs replacing.
There is a trip home to the Philippines.
Someone gets married.
The roof needs repairing.
The children need something.
Life happens.
And suddenly the financial target you were chasing has moved again.
There is absolutely nothing wrong with waiting until you are financially ready. In fact, you should be financially ready.
But there is a big difference between:
“I need more time to prepare.”
and
“I will start when everything is perfect.”
Perfect rarely arrives.
There will always be another expense, another uncertainty and another reason to wait.
Building wealth is usually not one dramatic moment where you suddenly have an enormous pile of extra cash and announce:
“Okay everybody, investment time!”
It is planning.
Saving.
Learning.
Running the numbers.
Then making a calculated move when the opportunity and your finances make sense.
Your Ipon Worked Hard to Get Here
Filipino families know sacrifice.
Many came to Canada and started again. They worked long hours, took extra shifts, raised families, helped relatives and saved whatever they could.
That deserves respect.
And protecting that hard-earned money matters.
But eventually there is another question worth asking:
Is my money only sitting there, or am I giving it an opportunity to grow?
Real estate can be one way to build wealth.
Not every property.
Not every deal.
Not every shiny new condo someone sends you with “LAST 2 UNITS!!!” written in all caps.
But with the right property, the right numbers, the right strategy, and the right real estate agent to walk you through what can be a tough decision, real estate can become part of a bigger financial plan.
A good real estate agent should not simply tell you:
“Bili ka na.”
They should help you understand what you are buying, look at the numbers, explain the risks, discuss your options and be willing to tell you when something doesn't make sense.
Maybe It’s Time to Put Your Ipon to Work
If you have been thinking about real estate but keep wondering whether you have enough money, enough income or enough knowledge to begin, start with a conversation.
Talk to RCC Real Estate Group.
We will help you look at your options and figure out what makes sense for your finances, your goals and your future.
No pressure. No pamahiin. No magic formula.
Just a plan.
Because you already know how to work hard for your money.
Now let’s see how your money can work hard for you.
Expert Advice, Expert Results.